15 Personal Finance Tips for 2026 to Build a Family Money Plan
Strong personal finance tips are not about extreme frugality or complicated spreadsheets. They are about small, repeatable habits that make your money work while you focus on your life. In 2026, with rising costs and endless digital temptations, a clear family money plan is the difference between stress and calm. This guide walks you through fifteen practical moves you can start this week.
I have coached households through debt payoff, first homes, and college savings, and the winners always share one trait: consistency. You do not need a finance degree. You need a simple plan and the discipline to follow it.
Why These Personal Finance Tips Matter in 2026
Financial stress affects sleep, relationships, and health. A plan replaces anxiety with control. When you know where your money goes, every decision gets easier, from a grocery run to a career change. The Consumer Financial Protection Bureau reports that households with a written budget and an emergency fund weather income shocks far better than those without.
The goal is resilience: enough cushion to absorb surprises and enough structure to keep moving toward your goals.
Foundational Money Habits Every Household Needs
Start here. These basics support everything else in your plan.
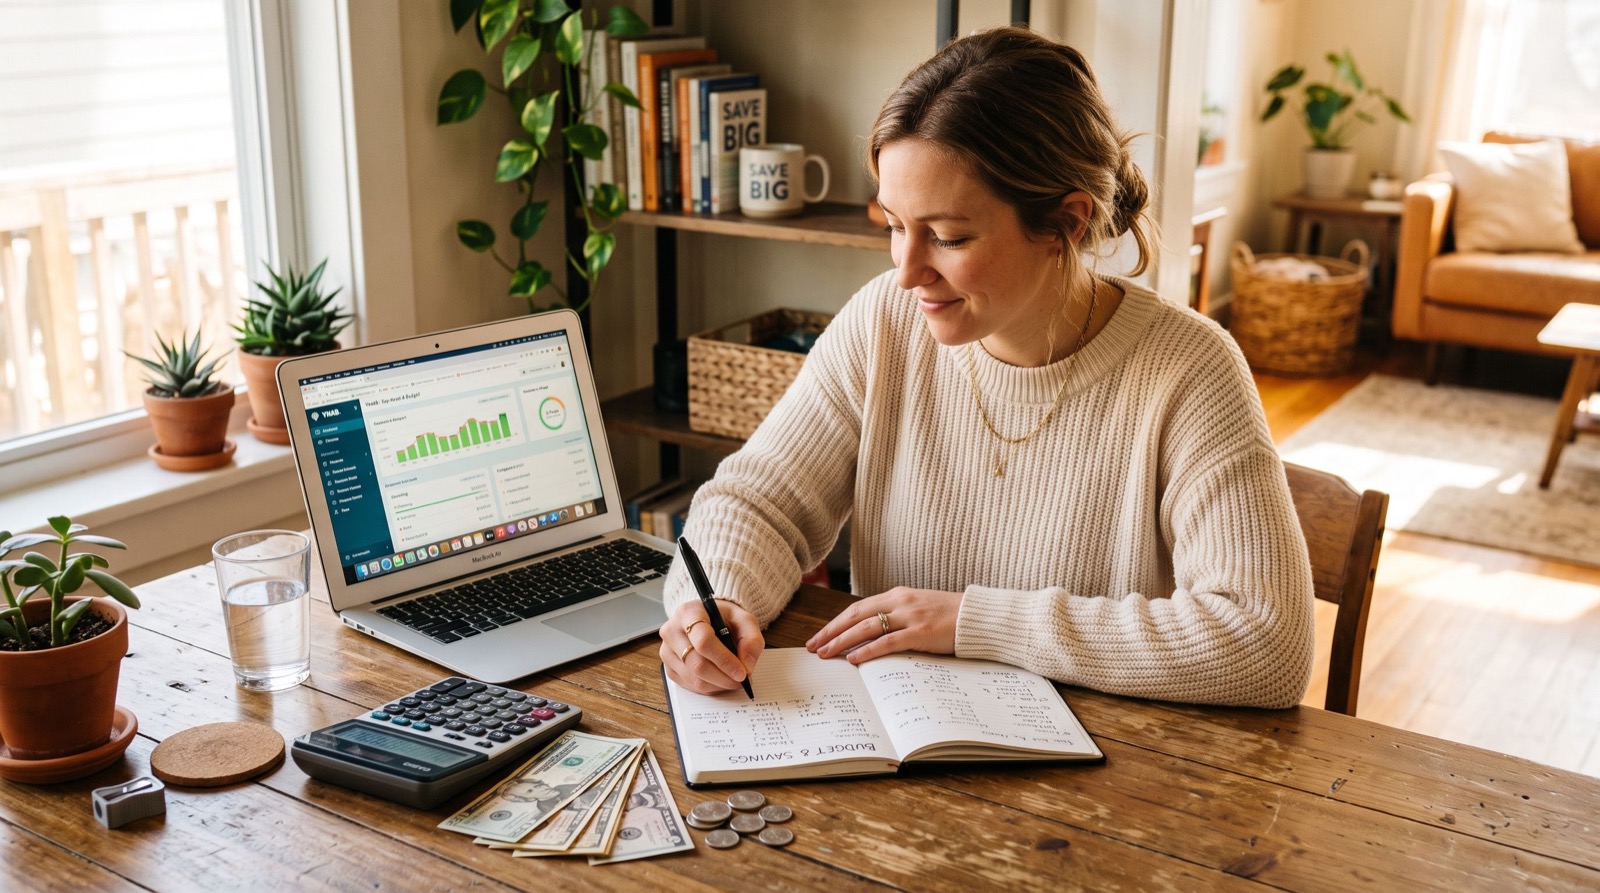
- Track every dollar for 30 days. Awareness alone changes spending.
- Build a starter emergency fund. Aim for one month of expenses, then grow it to three to six.
- Use a zero-based budget. Give every dollar a job before the month begins.
- Automate your savings. Pay yourself first on payday, before bills tempt you.
- Review subscriptions monthly. Cancel what you forgot you were paying for.
Smarter Spending and Saving Strategies
Once the foundation holds, optimize. Each of these tips frees up cash without a painful lifestyle cut.
- Follow the 50/30/20 rule as a starting split: needs, wants, and savings or debt.
- Plan meals weekly to slash the single most wasteful household category.
- Negotiate recurring bills like insurance and internet once a year.
- Buy quality once on items you use daily to avoid repeat purchases.
- Use a 24-hour rule on any non-essential purchase over fifty dollars.
Here is a comparison of three popular budgeting methods so you can pick the one that fits your family’s style.
| Method | How It Works | Best For |
|---|---|---|
| 50/30/20 | Split income into needs, wants, savings | Beginners who want simplicity |
| Zero-based | Assign every dollar a purpose | Detail-oriented planners |
| Envelope system | Cash or digital limits per category | Overspenders who need hard limits |
How much should a family keep in an emergency fund?
Most planners recommend three to six months of essential expenses. Dual-income households with stable jobs can lean toward three months, while single-income families or those with variable pay should target six. Start small; even a five-hundred-dollar buffer prevents most minor emergencies from becoming debt. Build it automatically so progress does not depend on willpower.
Using Technology to Stick to the Plan
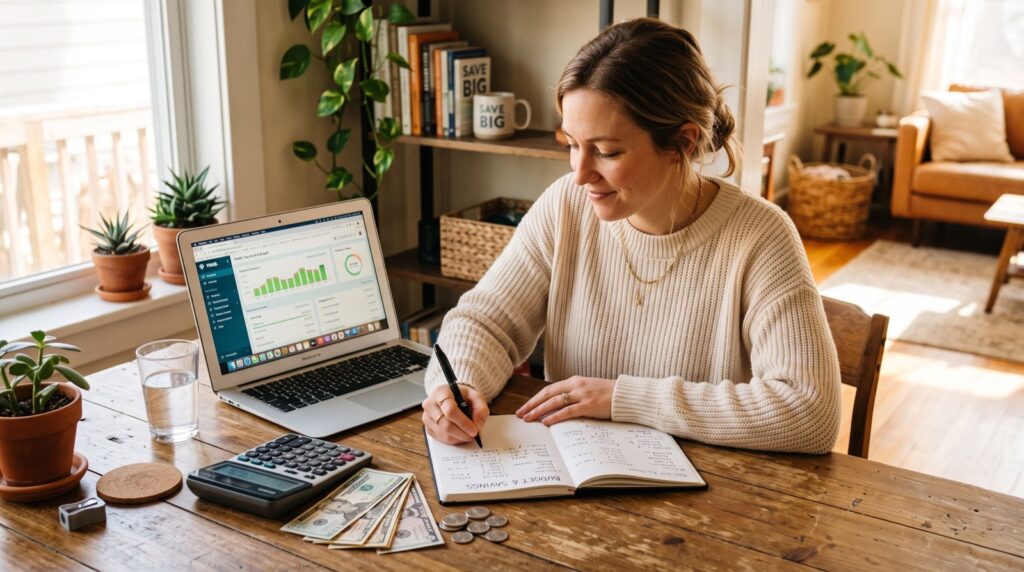
Willpower fades, but automation does not. The right apps keep your plan running on autopilot. Pairing a budgeting tool with the best money apps for saving and investing turns intentions into results. Set recurring transfers, enable low-balance alerts, and let round-up features grow your savings in the background.
One original tip from the field: schedule a monthly 20-minute “money date” with your partner or by yourself. Review the past month, celebrate one win, and set one focus for the next month. Treating finances as a short, regular ritual removes the dread and keeps everyone aligned on the same goals.
Planning for Big Life Events
Families face major expenses: moving, a new baby, college, or a home purchase. Each deserves its own sinking fund, a dedicated savings pot you contribute to monthly so the cost never arrives as a shock. When you need to hire help for a complex move or renovation, choose dependable specialists and budget for the full service rather than cutting corners that cost more later.
For retirement, start early and let compounding do the heavy lifting. The U.S. Securities and Exchange Commission’s compound interest calculator shows how even modest monthly contributions grow dramatically over decades. Time in the market beats timing the market every time.
Teaching Kids Healthy Money Habits
A family money plan works best when everyone understands it. Children who learn about saving early carry those habits into adulthood. You do not need a formal curriculum; everyday moments teach the most.
- Use a clear jar or app so young kids can watch savings grow visibly.
- Give a small allowance tied to simple chores and let them make spending mistakes while the stakes are low.
- Involve teens in real decisions, like comparing grocery prices or planning a trip budget.
- Model calm money talk. Kids absorb your attitude toward money more than your rules.
Making money an open, normal topic at home removes the shame and confusion that trip up so many adults. It turns your plan into a shared family value rather than a set of restrictions handed down from above.
Avoiding Common Money Mistakes
Even disciplined households slip. Watch for lifestyle inflation, where every raise is instantly absorbed by higher spending instead of higher saving. Guard against relying on credit for routine expenses, and resist comparing your finances to curated social media lifestyles. The quiet, consistent saver almost always finishes ahead of the flashy spender.
Frequently Asked Questions
What are the most important personal finance tips for beginners?
Track your spending, build a small emergency fund, and automate savings. These three habits create the foundation everything else is built on. Avoid trying to optimize investments before you have a cushion and a budget. Master the basics first, then layer in more advanced strategies as your confidence grows.
How do I start budgeting if I have an irregular income?
Base your budget on your lowest typical monthly income, and treat anything above that as a bonus to save or pay down debt. Build a larger buffer, ideally six months, to smooth out lean months. A zero-based or envelope method works especially well because it forces every dollar to have a plan.
Should I pay off debt or save first?
Do both in a sequence. First save a small starter emergency fund so you stop adding new debt during emergencies. Then attack high-interest debt aggressively while making minimums elsewhere. Once high-interest balances are gone, redirect those payments into a fuller emergency fund and investing.
How often should a family review its budget?
Check in briefly every week and do a deeper review monthly. Weekly check-ins catch overspending early, while the monthly review lets you adjust categories and celebrate progress. Quarterly, revisit bigger goals like insurance, subscriptions, and savings targets to keep the whole plan current.
Final Thoughts
The best personal finance tips share one theme: start small and stay consistent. Track your money, automate your savings, plan for big expenses, and review regularly. You do not have to overhaul everything overnight. Pick two tips from this list, put them into action this week, and let steady habits build the secure family money plan you deserve in 2026.